Texas Hail Damage Car Insurance Claims: Deductibles, Repair Estimates, and Next Steps
Hail damage to your own car is generally a comprehensive insurance claim, subject to your policy and deductible. Liability coverage alone does not pay to repair your vehicle after a hailstorm. Check the coverage that was in force when the storm occurred, document the damage, and contact the insurer before committing to major repairs.
For a Texas driver looking at dents across a hood or roof, the questions quickly become practical: Is the repair above the deductible? What if the shop finds more damage? Could a car that still runs be a total loss? Work through the claim in stages so that a repair estimate, an authorization, and an insurance payment are not confused.
First confirm comprehensive coverage and the loss date
The Texas Department of Insurance's hail-claim guidance identifies comprehensive as the relevant auto coverage. Comprehensive coverage is optional unless a lender or lease requires it. Look at the declarations page for the particular vehicle, then check the policy terms and deductible. A household with several cars may not have the same coverage on each one.
Record when and where the car was damaged, including the storm date, as accurately as you can before contacting your insurance provider. Report hail damage promptly and ask your insurance provider about the reporting requirements in your policy. Tell the adjuster about older dents, prior claims, or unrepaired damage rather than attributing everything to the latest storm. Adding comprehensive after the event does not make the earlier hail damage covered.
If you are unsure whether the damage was caused by hail, describe what you observed and let the appropriate inspection address the cause. A photograph can document a mark without establishing when it happened. Accurate information helps the insurer separate the current claim from another event.
Document the car before repairs begin
TDI recommends prompt reporting, photographs or video, a damage list, and steps to prevent additional damage. When safe, take clear photos from multiple angles, including wide shots and close-ups of affected panels and glass to document the loss. Keep the originals and note the date and location. Do not put yourself in an active storm or unsafe traffic situation to collect photographs.
-
Record the vehicle's identifying details and the areas that appear damaged.
-
Photograph the roof, hood, trunk, exposed side panels, and glass as relevant.
-
Include the windshield and any paint damage in the photo set.
-
List any water entry or interior damage separately from exterior dents.
-
Keep receipts for reasonable temporary protection or transport and ask whether they are covered.
-
Save the claim number and the adjuster's contact information in one place.
When filing claims, the insurance company may send an adjuster for inspection, so avoid permanent repairs before that review.
If glass is broken or another condition makes the car unsafe, discuss transport and temporary protection with a qualified repair provider and the insurer. Ask before discarding damaged items or approving permanent work that could affect inspection. Emergency protection and a final repair authorization are different steps. Texas has deadlines for acknowledging and handling claims on your own policy, with exceptions and possible catastrophe extensions. Review the TDI auto-insurance guide and ask which deadlines apply to your claim.
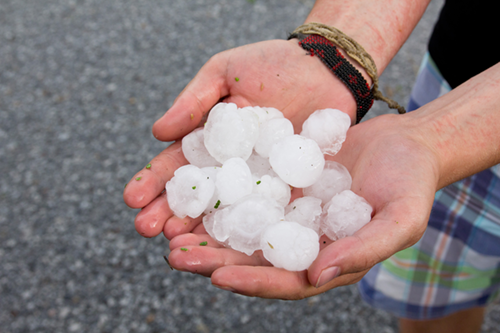
Calculate the deductible against an actual estimate
The comprehensive deductible is the portion of a covered loss you bear under the policy. It may differ from the collision deductible. Do not use the number from a homeowners policy or assume that the auto deductible is a percentage of the car's value.
Hypothetical example: an accepted hail repair estimate is $3,600 and the applicable comprehensive deductible is $1,000. Ignoring other adjustments, the insurer's share would be $2,600 and the policyholder's share $1,000. If the covered repair amount were $800 with that same deductible, the calculation would not produce a payment. These are arithmetic examples, not Texas averages or a quoted claim offer.
Ask the adjuster to explain each deduction in the estimate. If the repair shop later submits higher repair costs, do not assume the insurer has accepted them. Find out which items are approved, which remain under review, and what you would personally owe before authorizing additional work.
Understand the estimate and supplement process
A first estimate describes the damage identified at that stage. The TDI auto-insurance guide explains that the shop or policyholder can discuss a higher estimate with the adjuster when more damage is found. Ask who submits the supporting photographs and itemized supplement, and whether the car needs another inspection.
|
Document |
What it helps establish |
Question to ask |
|---|---|---|
|
Initial estimate |
The currently identified repair scope and cost. |
Which panels, glass, labor, and materials are included? |
|
Repair authorization |
What you are allowing the shop to do. |
Could I owe for work the insurer has not approved? |
|
Supplement |
Additional damage or cost identified after the first estimate. |
Has the insurer accepted this addition? |
|
Final invoice and payment explanation |
The completed work and how payment was calculated. |
Do the deductible and any remaining balance match our agreement? |
TDI says an insurer can suggest preferred repair shops, but Texas drivers can choose their repair shop after hail damage. Ask a prospective shop about its warranty, timetable, and process for working with your insurer. Ask about repair options, including paintless dent repair for minor hail damage when appropriate. A shop's advertised convenience or deductible offer does not change your insurance contract; request the complete written cost arrangement.
A drivable car can still raise a total-loss question
The relevant comparison includes repair cost and the vehicle's value, not simply whether a car is severely damaged after a storm. TDI's total-loss guidance explains that a company may total a car when repairs approach or exceed its value, and sometimes below that level. When a total-loss decision is made, the insurer generally compares repair costs and salvage value with the vehicle's actual cash value. Ask how the insurer reached its valuation and which vehicle details it used.
Actual cash value is the starting point, and you can challenge the insurance company's number with comparable vehicles for sale in your local area. Check the model, trim, mileage, condition, and equipment in the valuation report. If something is wrong, provide documentation. Comparable local vehicles can help frame a discussion, but asking prices for materially different cars do not establish what your car was worth. Keep the conversation focused on comparable condition and features.
If you want to retain the vehicle, discuss how keeping it can reduce the payout by the salvage value before agreeing. A hail-only total loss may not always trigger a salvage title in Texas. Do not assume every hail total loss receives the same title classification or that keeping the car automatically permits it to be driven. Confirm the applicable Texas DMV requirements for the specific title status.
A loan balance is a separate figure from the vehicle's insurance value. If you own the car outright, the settlement money may go directly to you, while someone who still owes money should also review any existing gap protection and its terms. If the settlement is below what you owe, ask about any existing gap protection and its terms. Do not assume a standard comprehensive claim pays off the entire loan.
Ask about transportation and payment timing
Hail repairs can interrupt a commute even when the damage initially looks cosmetic. Check whether your purchased policy includes rental reimbursement for this covered loss. Ask about the daily limit, total limit, approved dates, billing arrangements, and cutoff if the car is declared a total loss. Comprehensive coverage should not be treated as an unlimited rental benefit.
Ask who will receive the claim payment, especially when a lender has an interest in the vehicle. Save the written explanation and confirm what must happen before repairs or a replacement purchase. Avoid planning around an exact payment date that the insurer has not confirmed.
Questions Texas drivers often ask
Will a hail claim definitely increase my premium?
Hail damage typically falls under comprehensive coverage. There is no reliable universal premium answer for every policy and renewal. Ask the insurer how it treats the claim and what other rating factors may change. Do not treat either “no increase” or a fixed percentage increase as guaranteed.
Should I repair every dent before the adjuster sees the car?
Coordinate inspection and repair authorization first to handle hail damage, while taking reasonable steps to prevent more damage, and work through the claims process to cover hail damage before authorizing permanent repairs. If urgent work is needed, explain the situation to the insurer and keep documentation. Unrepaired or older dents can create disputes over pre-existing damage, so keep your photos, receipts, and notes until the insurer reviews the car. Do not assume an unreviewed invoice will be paid in full.
What if I disagree with the estimate?
Identify the disputed items and provide supporting information to the adjuster. Ask about the policy's review or appraisal provisions if the disagreement remains. TDI's consumer resources can explain complaint options; a complaint does not guarantee a particular payment.
Review hail protection before the next storm
Hail damage is a recurring concern for Texas drivers. Read our Texas auto insurance coverage guide to compare liability, comprehensive, collision, and optional benefits. Protect your vehicle with a garage or other covered parking when possible. If you want to review policy options, request a Texas vehicle insurance quote or call 844-431-1234. If you are considering a protective car cover, check its stated limitations; do not assume it prevents all hail damage.
Published by Texas Vehicle Insurance. Texas Department of Insurance sources checked October 19, 2026; total-loss guidance updated July 23, 2026. Coverage and claim outcomes depend on the policy and loss details.